Sunday, 27 October 2013

Callaway Golf Fore!

Callaway (ELY) is one of the best known golf brands in the world selling its products in more than 70 countries worldwide. However since the passing of its founder in 2001 ELY has struggled as the brand became less focused on drivers and clubs and its core golf users.

The golf industry as a whole has suffered from the financial crisis with industry golf sales down 13% from the 2007 peak. Within this decrease ELY has consistently lost market share as competitors such as TaylorMade (owned by Adidas) and Titleist (owned by Fila) stepped up marketing and innovation. However there are signs of a turn around with ELY's marketshare of 15.1% year to date up 1.1% on last year (See ELY marketshare below). Importantly their latest results are showing signs of profitability with expectations for a 2013 pre tax income.


In the CEO's words "with that said, our turnaround is proceeding at or above our original expectations, particularly given the headwinds we experienced this year from unfavorable changes in foreign currency rates, adverse weather conditions, a very late start to the 2013 golf season, and higher than normal promotional activity in both North America and Europe."

The turnaround
New management, a change in marketing, product execution and a reduction in cost structure have helped. The new CEO brought in last year Oliver Brewer has streamlined their business by selling the Ben Hogan and Top Flite brands. 

He also licensed the apparel operations to third parties so that ELY could focus on its core club and ball business. ELY's cost structure was reduced to $340 million down from last years run rate of $380 million in expenses reducing the number of employees from 1,800 to 1,500 as of December 2012.

ELY beefed up marketing signing endorsement deals with Phil Mickelson, Ernie Ells and Ryo Ishikawa. Though Phil Mickelson was recently spotted using a TaylorMade driver. Apparently Phil has one of the most flexible equipment contracts of any top player and can play with other brands from time to time.
View image on Twitter


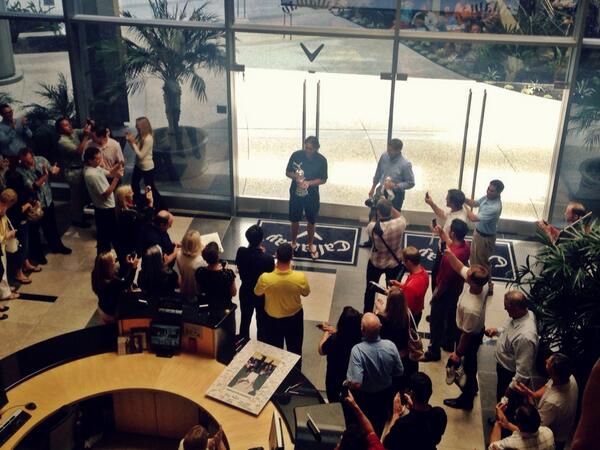
Phil at Callaway HQ thanking the staff for their support after British Open win.

The back nine
Golf becomes an Olympic sport at the 2016 Rio games with the 2020 games awarded to Tokyo. Japan is the largest international market for ELY. There is also the Chinese golfing opportunity, with gold medals now on offer and China's historic dominance in sports involving  mental focus golf in China will surely be a driver of growth.

After years in the rough ELY now looks to be finishing under par.

Jason


Disclosure: Decisive has no long position in Callaway (ELY) stock 

The material in this article is for informational purposes only and in no way constitutes a solicitation of business or investment advice. The material has been prepared without regard to any client's or other person's investment objectives. Before making an investment decision you should consider the assistance of a financial adviser and whether any investment or service is appropriate in light of your particular investment needs.

Sunday, 20 October 2013

A Chinese Gumtree

58.com is China's largest online marketplace. Similar to GumTree here in Australia and Craigslist in the US 58.com enables local merchants and consumers to share information and conduct business.

58.com had approximately 4.3 million active local merchants out of an estimated 53 million small medium businesses in China. 58.com is the leader in online classifieds with 38% market share by revenue and 86 million monthly unique visitors. Its rivals include Ganji and Baixing though 58.com has 2x and 9x more revenue respectively than these competitors (see chart below).


Big partners
58.com introduced Alipay (owned by Alibaba) services earlier in the year. Alipay is similar to Paypal but differs in that is more like an escrow service. So just like Taobao customers 58.com consumers can decide to release payment after having enjoyed a service or bought a second hand item. This was the first time that Alipay had developed a custom solution for a third party and helps overcome the lack of trust in buying online in China. A survey conducted by 58.com shows that 90% of its users trust Alipay and 75% have Alipay accounts.

58.com has also begun to use Baidu (Google of China) new light app feature. So users will be able to search through the app without having to physically download the application on the mobile. Around 40% of 58.com page views were on mobile applications.

Show me the money!
Like most internet companies 58.com earns its revenue through advertising. Though the majority 60% is subscription based. A membership gets merchants an online storefront, preferential listing benefits and a higher quota for daily listings. These contracts typically last from one month to a year. Approximately 273,000 merchants subscribe to the service. Renting, jobs and their yellow pages services are the most popular.


58.com has begun focusing on advertising to drive more growth. Only 18% of 58.com's paying merchant members used online marketing services. 58.com have also rolled out realtime bidding similar to Google adwords this allows merchants to bid real time on certain keywords to improve the chances of their listings being seen and sold.

China has 45 cities with a population greater than 2 million this compares to only 4 cities in the US. Given the low monetisation compared to peers the stock is one to watch. 58.com's IPO will price at the end of the month.

Jason


Disclosure: Decisive has no long position in 58.com (WUBA) stock 

The material in this article is for informational purposes only and in no way constitutes a solicitation of business or investment advice. The material has been prepared without regard to any client's or other person's investment objectives. Before making an investment decision you should consider the assistance of a financial adviser and whether any investment or service is appropriate in light of your particular investment needs.


Sunday, 13 October 2013

Nike just doing it

Nike (NKE) last week hosted their 2013 investor meeting. As the CEO Mark Parker stated "Nike is designed to win". For such a large company NKE's long term goals are impressive, they plan to grow revenues at a high single digit % and grow earnings per share at a mid teens rate. NKE already has the majority of marketshare in their main categories of running and basketball. Fortunately the overall market is growing because of globalisation.

Over the next decade, we will see the world's middle class population grow by 1 billion consumers. NKE seems positioned to be the shoe for athletes and weekend warriors around the world. NKE is dominant in two categories with running the “heart” of the NKE brand and Basketball the “soul”. In fact in the United States NKE basketball holds upwards of 90% market share.

Jordan more popular today than in his playing days

Michael Jordan is its own brand. Amazingly when the first Air Jordan was released back in 1985 the shoes were banned by the NBA because they did not have any white on them. Jordan wore the shoes anyway and every time he stepped on the court he was fined $5,000. Nike of course used this as a marketing tool hinting that the shoes had a certain edginess to them. Brand Jordan is now selling 3x more today than when Michael Jordan was playing.

Custom made shoes are coming

NikeId has customised shoes that lets customers choose colours and styles. Hope not many choose this option below but glow in the dark elephant print is available to help you stand out at night and be somewhat subtle during the day. NKE believes in over two years time they will be able to scan your foot and have a shoe created specifically for you.


All about innovation
NKE is at the forefront of innovation using digital technology with Nike+ and the ability to customise shoes. Their latest invention the Flyknit shoe is meant to feel like a sock not a shoe. When customers/athletes first wear the shoe they start looking down at their feet because they forget they are wearing shoes! It might be strange at first but apparently its hard to go back to a normal shoe.

NKE also leads digitally with NIKE+ which lets 20 million members track activities like running and helps you to set and achieve fitness goals. They have run over 1 billion miles. This is important for NKE as they receive information on runners activities so they customise their NKE experience based on their habits.

Finally for NIKE women is a huge opportunity. Today, in North America NKE's Women's business makes up less than 25% of overall business.

Jason


Disclosure: Decisive has no long position in Nike (NKE) stock 

The material in this article is for informational purposes only and in no way constitutes a solicitation of business or investment advice. The material has been prepared without regard to any client's or other person's investment objectives. Before making an investment decision you should consider the assistance of a financial adviser and whether any investment or service is appropriate in light of your particular investment needs.


Sunday, 6 October 2013

Twitter

Twitter has announced details for its upcoming public listing. It is being compared to Facebook already but what makes it different is its focus on public real time news. Twitter is a broadcast system anyone can follow anyone, Twitter has become the way to find out what is happening here and now. To me it sits in between Facebook which is personal news and Linkedin which is business news. Twitter is general news and I think advertising is seen as more acceptable if it relates to news you are following versus advertisements next to personal pictures on Facebook.

There are no concerns over mobile as 75% of Twitter users accessed the service from a mobile device in the second quarter with 65% of advertising revenue generated from mobile. That's more than the 71 percent and the 41 percent, respectively, for Facebook in the same period. Twitter is a more mobile friendly product as both companies began displaying mobile advertisements last year but Twitter has seen more mobile penetration.

Key stats
Twitter Facebook
Employees 2000 5300
Risk pages in S1 32 22
Stock structure One class  Two class super voting
Monthly users 218 million 1.15 billion
International revenue 25% 55%
Mobile usage 75% 71%


In a refreshing change there will only be one class of stock unlike most technology companies a founder does not have absolute control over the company. This is more shareholder friendly as it gives everyone a say in how the company can be run and gives other investors the opportunity to take it over. Twitter has also disclosed more risks than Facebook running at 32 pages versus Facebook's 22.

Risks
Twitter is not making money. As can be seen above Twitters revenue per user is much smaller.
Another key risk is the fact that a lot of Twitter content is accessed elsewhere. This is a risk as if Twitters news is accessed elsewhere they will not receive advertising revenue. Twitter has not disclosed the number of users who access their content through other applications that do not contain their ads.

News
One of Twitters key attractions is the ability to follow well known personalities. It is a broadcast platform to find out directly what key people are saying. A number of corporates like Tim Cook and Carl Icahn have just come on board but most surprising to me is Warren Buffet joined a few months ago. Buffet signing up is fascinating considering his aversion to technology. Apparently he resisted his friend Bill Gates (founder of Microsofts) attempts to set up a computer in his home. As more celebrities join the service Twitter should get more and more popular.

There has not been much talk about Vine which is a 6 second looping video. The service was launched by Twitter at the start of the year and their most recent announcement suggested they had 40 million users in August. They are facing more competition from Instagram which has released a 15 second video system but it was interesting that Vine was not mentioned more in the S1.

Revenue
Twitter only began advertising and focusing on revenue in 2010. They recently launched self serve advertising in the US with intentions to launch in a platform in international markets. Self serving advertising is key for most businesses as it allows advertisers to purchase on Twitter through an online platform (much like Google adwords) rather than than through their direct sales force or resellers.

There is no news on the valuation yet but whatever you do please don't buy TWTRQ. Twitter has not listed yet. The TWTRQ ticker is for Tweeter Home Entertainment! Investors seemed to have a case of mistaken identity they are a retailer of home entertainment systems. Shares jumped from 2 cents to 12 cents before trading was halted unfortunately for those investors the company is bankrupt!

Luckily for Twitter there has been no movie made about the founding of the company like Facebook which had a movie (the social network) released ahead of listing. But Twitter has received some attention on Saturday Night Live, see below. # Hashtag!


Jason
Disclosure: Decisive has no long position in Twitter (TWTR) stock 

The material in this article is for informational purposes only and in no way constitutes a solicitation of business or investment advice. The material has been prepared without regard to any client's or other person's investment objectives. Before making an investment decision you should consider the assistance of a financial adviser and whether any investment or service is appropriate in light of your particular investment needs.

Sunday, 29 September 2013

Empire State Building

Investors can finally own a piece of the Empire State Building. The Empire State will be a part of a real estate investment trust that will list with 100% exposure to Manhattan and Greater NY Metropolitan market offices and retail. The portfolio of buildings has been assembled over an 80 year period which has been consolidated into one public company. What makes this company special is not only the Empire State Building but the observatory.

Even the famous antenna makes money
The Empire State Building is the flagship property and accounted for 45.5% of total pro forma revenues for the six months ended June 30, 2013. Included in this number was the observatory which on its own contributed 18% of revenues in 2012. Last year 4.15 million visitors took the lifts up to the 86th and 102nd floor observatories. Over the past 5 years ticket prices have increased from $15.47 to $20.21. The observatory does show some tourism cyclicality with negative growth in 2001 and 2009 but has tended to grow at a low double digit pace.


Remember the famous antenna that King Kong climbed, well that antenna made $17.1million last year luckily he didn’t break it. The building has 150 antennas which are licensed to 35 third party television and radio broadcasters and made up 9.5% of the Empire buildings revenue. These customers include CBS, Univision, FOX, ABC and NBC.


King Kong lego style at New York Toys R Us


What else do they own?
As of June 30, 2013, they owned 12 office properties (including one long-term ground leasehold interest) encompassing approximately 7.7 million rentable square feet of office space, which were approximately 83.5% leased.

Why list? Upgrades are needed
The company currently estimates that between $95.0 million and $125.0 million is needed beyond 2013 to complete substantially the renovation program at the Empire State Building. This is expected to be finished by the end of 2016. The goal is to re position the building for new higher credit quality tenants including Linkedin, Coty and even Shutterstock.

The risks are tenant concentration. Currently LF USA, Coty, Inc., Legg Mason, Warnaco, a subsidiary of PVH Corp, and Thomson Reuters are the largest customers. Together they represented 22.2% of the portfolio’s base rent as of June 30, 2013.

At the end of the day what is special about this listing is the Empire State Building. If King Kong wants it it must be special!

Jason

Disclosure: Decisive has no long position in Empire State Realty Trust (ESRT) stock 

The material in this article is for informational purposes only and in no way constitutes a solicitation of business or investment advice. The material has been prepared without regard to any client's or other person's investment objectives. Before making an investment decision you should consider the assistance of a financial adviser and whether any investment or service is appropriate in light of your particular investment needs.


Sunday, 22 September 2013

Adobe in the cloud

Adobe (ADBE) is famous for its photoshop editing tool and acrobat pdfs. For users Photoshop has become a verb we don't edit photos we photoshop photos. Becoming a verb is valuable and as an investor is something I focus on. ADBE has a great history in enabling content now they want to also manage, measure and monetize as content goes digital.

13 million users have installed their creative editing products. This is a market that continues to grow with devices like the smartphone and tablet increasing demand for content. ADBE has made the courageous decision to move from a perpetual software licensing system (one off purchase) to a recurring software as a service model called Creative Cloud. This means ADBE will develop two key business traits that investors favour subscription revenue and the cloud.

Subscription revenue and the end of piracy Aarghh!
Recurring revenue is the holy grail for investors as the revenue tends to be predictable, scalable and stickier for users. ADBE licenses their creative cloud on an annual basis with monthly charges. At the moment 40% of ADBE revenue is recurring and should increase over time.


As we know with our mobile and internet subscriptions the recurring nature of direct debits rather than an outright purchase every year should be a better sales model for ADBE. Moving to a subscription model has other benefits,one being piracy. ADBE estimates that 90% of usage in China and India involved piracy in the US they estimate it to be 20%.

Everyone wants to be in the cloud.
The other holy grail is the cloud. Cloud services make a lot of sense in a global, mobile world. Cloud services like ADBE tend to be delivered over the internet (in ADBE case apps) no individual software or hardware installations needed. Cloud is useful as it allows users to collaborate on mobile devices/ipads and teams should have an easier job as they all work on the most up to date version. Because services are delivered through the internet updates can occur more frequently there will be no need to buy new software every year. Files, fonts and preferences will be stored in the cloud so they can be accessed anywhere. This also makes the service stickier as all your data is stored and kept with ADBE and not your computer. Another innovation will be the ADBE cloud connected pen. See video below.


Marketing
A new growth area is marketing, this division achieved growth of 28% in the recent quarter. ADBE believes they have the best end to end value proposition with Creative cloud and Marketing cloud. ADBE believe they can address the lifecycle of content from not only making and managing (Creative Cloud) to now measuring and monetising (Marketing cloud). In their words bridging the art of the creative with the science of digital marketing.

Jason

Disclosure: Decisive has no long position in Adobe (ADBE) stock 
The material in this article is for informational purposes only and in no way constitutes a solicitation of business or investment advice. The material has been prepared without regard to any client's or other person's investment objectives. Before making an investment decision you should consider the assistance of a financial adviser and whether any investment or service is appropriate in light of your particular investment needs.

Sunday, 15 September 2013

Living the dream at Dreamworks animation

Dreamworks Animation (DWA) is best known by families for its movies Shrek, Kung Fu Panda and Madagascar. DWA has historically released two films a year which on average take three years to five years to produce. This compares to live action/drama content which can be put together in months and not years. Because of the work required DWA does not have the large backlog with recurring revenues like other studios which help pay the rent if one of the two films is a bomb.

All this is beginning to change thanks to an acquisition and a new agreement.

The acquisition of Classic media which owns 3,600 hours of programming.
The agreement with Netflix to produce 300 hours of Dreamworks television shows.

What this means is a more steady revenue generating business. For studios backlog is extremely important as it is high margin revenue, production has already been expensed so any new sales are large contributors to the bottom line. With the two deals above DWA creates a larger backlog and with the television shows the potential to build its own network like the Disney channel.


Dreamworks greeter at the front door, reception this way!

Classic Media
The acquisition of Classic Media is a game changer for $155million DWA is now the proud owner of one of the world’s largest comic book archives in addition to media rights to the golden books library. The characters include Casper, Richie Rich, Postman Pat, Where’s Waldo, Rocky & Bullwinkle, Lassie, He-man, Voltron and more. See below.


Netflix deal
TV is a great business for studios as the revenues are more consistent as shows are multi-year agreements which can be extended further if successful. Owning a backlog of TV shows can also help DWA to build their own children’s television network channel in the future. Over a four year period DWA will produce nearly a billion dollars worth of programming. The slate has been pre-agreed without any performance requirements. In general the deal has an extensive period of exclusivity after which DWA can sell the content in later distribution deals.

China
The Chinese media market is heavily regulated and restricted. Fortunately DWA has teamed up with Shanghai Media Group to create Oriental Dreamworks a Chinese themed animated and live action film company including theme parks, games and consumer products. The studio's first animated film will be Kung Fu Panda 3. Because of Kung Fu Panda DWA is immensely popular in China with four of China's top five animated films produced by DWA. Oriental Dreamworks has the potential to become the Disney/Pixar of China as the no.1 animated player.

Jason

Disclosure: Decisive has no long position in Dreamworks (DWA) stock 
The material in this article is for informational purposes only and in no way constitutes a solicitation of business or investment advice. The material has been prepared without regard to any client's or other person's investment objectives. Before making an investment decision you should consider the assistance of a financial adviser and whether any investment or service is appropriate in light of your particular investment needs.